
Does FEMA pay for mold remediation?
Short answer
Sometimes. After a federally declared disaster, FEMA's Individuals and Households Program may give homeowners Home Repair funds to clean up, remove or remediate disaster-caused mold, but only when FEMA verifies the mold makes the home unlivable. FEMA won't pay for losses your insurance covers. Apply at DisasterAssistance.gov, file your insurance claim too, and document everything from day one.
What FEMA says
According to FEMA’s guidance on mold damage, the agency may provide funds to address mold through its Individuals and Households Program (IHP). There are two routes:
- Home Repair assistance. Homeowners may receive Home Repair funds for the clean-up, removal or remediation of disaster-caused mold. To qualify, FEMA has to verify that you can’t live in your home because of that mold damage.
- Clean and Sanitize Assistance. For minor disaster damage where you can safely stay in the home, renters and homeowners may be eligible for limited funds meant to prevent further loss and health and safety problems, such as mold growth.
Both depend on a federal major disaster declaration that makes Individual Assistance available in your county. After Hurricane Ian in 2022, for example, the declaration (FEMA-4673-DR) designated Lee, Collier and Charlotte counties for Individual Assistance. Mold from a slow leak or a failed AC drain line, outside a declared disaster, isn’t something FEMA covers.
How insurance fits in
Federal law requires FEMA to make sure nobody is paid twice for the same disaster loss. FEMA calls this duplication of benefits. In practice:
- File your insurance claims as soon as you can.
- Apply for FEMA assistance anyway, even while your insurance claim is pending. FEMA may be able to help with losses insurance won’t cover.
- Report all your coverage when you apply, and send FEMA your insurance settlement or denial when you get it.
Flood insurance is its own question. FEMA’s mold guidance states that National Flood Insurance Program policies will not cover damage from mold, and the NFIP flood policy excludes mold and moisture damage within the policyholder’s control, including failing to inspect and maintain the property after the flood water recedes. Homeowners policies vary, and many limit mold coverage, so read the mold or fungi section of yours. Our national page on whether homeowners insurance covers mold remediation explains the general rules, and Florida homeowners insurance and mold covers the Florida side.
Why acting fast matters for your application
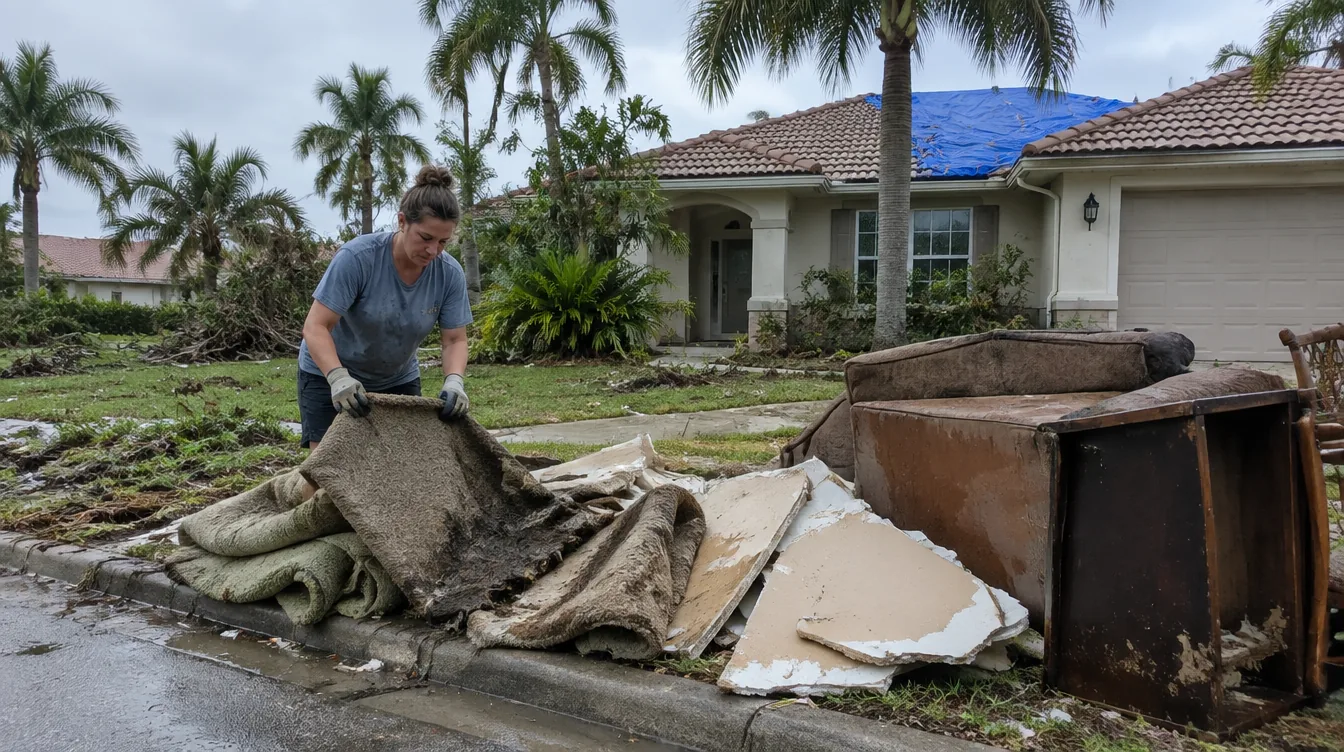
FEMA strongly encourages owners to begin clean-up and documentation right after a flood, if the property is safe to enter, to prevent mold from growing and spreading. The EPA advises drying water-damaged materials within 24 to 48 hours. In Southwest Florida heat, with the power often out, that window is short. Showing that you acted quickly protects both a FEMA application and any insurance claim.
What to keep
- Dated photos and video of every room, the waterline and damaged belongings, taken before anything is moved
- Receipts for fans, dehumidifiers, cleaning supplies and any work you pay for
- Moisture readings and a record of what was removed and when
- The independent assessor’s inspection report, lab results and scope
- The final clearance report
- All letters and decisions from your insurer and from FEMA
Mistakes we see after Southwest Florida storms
- Throwing things out before photographing them. Put soaked items at the curb only after they’re documented.
- Not applying because you have insurance. FEMA says to apply even while your insurance claim is pending, so any gap can be looked at.
- Closing walls too soon. New drywall over wet block or framing is how storm mold shows up again a year later, and it erases the evidence of what happened.
- Hiring whoever knocks first. Florida licenses mold assessors and remediators. Check any license with the Department of Business and Professional Regulation before you sign.
If FEMA says no
A FEMA decision letter explains why assistance was denied or limited, and it tells you how to appeal. Common problems are missing documents, an insurance decision FEMA hasn’t received yet, or a finding that the home is still livable. Read the letter carefully, send what’s missing and keep copies of everything you submit.
How we help after a storm
We can’t tell you whether FEMA or your insurer will pay, and we don’t handle applications for you. What we can do is keep the records they ask for. On our hurricane and flood mold remediation projects, an independent licensed mold assessor inspects and samples the home, writes the scope and performs clearance testing. We do the remediation to that protocol and keep photos, moisture logs and a list of what was removed at every stage.
We're done when the lab says so.
Every remediation ends with clearance testing, and our work is backed by a complete-removal guarantee. We don't close a job on a failed result.
Talk to a specialistNeed documentation for your application?
Tell us what the storm did to your home. A Southwest Florida specialist will call you back and explain what records we keep.
Not sure yet? Try the free AI Mold Risk Check